How to Safely Handle Your Parents’ Retirement Portfolio Alongside Your Personal Intraday Trades
You trade intraday, and you also look after your parents’ retirement savings. Here is a simple framework to keep the two separate, stay authorized, and protect the money that matters most.
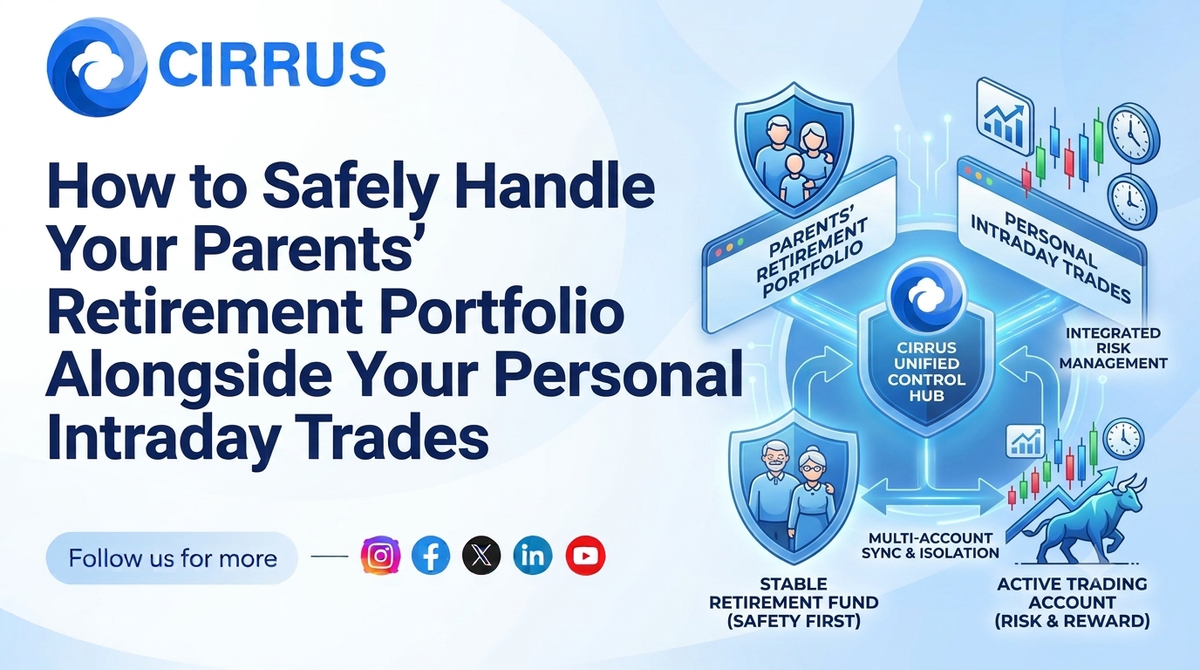
Many people end up as the family’s go-to person for investments. You trade intraday in your own account, and you also look after your parents’ savings, which they are counting on for retirement.
Those are two very different jobs. One is fast and high risk. The other is slow, steady, and should protect capital first. Keeping them separate is the most important rule.
The Short Answer: Can You Manage Your Parents’ Portfolio and Trade Intraday at the Same Time?
Yes, but only with clear boundaries. Your parents’ retirement money should follow a long-term plan agreed with them, with its own rules, and should not be pulled into your intraday strategy. Written consent, separate processes, and regular reviews keep both safe.
Why the Two Should Never Be Mixed
Intraday trading is built around short holding periods, tight stops, and accepting frequent small losses. Retirement money has the opposite purpose: preserve capital, earn steadily, and stay available when needed.
Mixing them creates three problems:
- Mismatched risk: A strategy that suits your appetite for risk may not suit someone who cannot afford a large drawdown.
- Confused decisions: When one workflow handles every account, it is easy to apply an intraday signal to a long-term account by mistake.
- Trust and accountability: Money managed for family needs a record of what was decided and why.
Practical friction adds to this. Brokers now expect API orders from a whitelisted static IP address, and session tokens reset daily, so account connections need care and deliberate setup.
A Simple Framework for Keeping Them Separate
1. Get clear authorization.
Only operate an account you are authorized to manage. Confirm with your parents what you can do, and check each broker’s rules for third-party access. Never share or store passwords informally.
2. Write down the plan.
Record the goal, the time horizon, how much risk your parents are comfortable with, and what you will and will not trade. Share it with them.
3. Keep strategies in separate lanes.
Intraday signals go to your own account. Long-term holdings follow the written plan, usually with far fewer trades.
4. Review on a schedule.
Set a monthly or quarterly check-in with your parents instead of reacting to daily moves.
5. Keep records.
Note major decisions and the reasoning, so there is always a clear trail.
How Cirrus Fits Into This Setup
If you use a multi-account terminal, the goal is to keep the right accounts attached to the right activity. Here is what Cirrus offers:
- Native Static IP Binding: Orders go through whitelisted static IP architecture on the cloud, so you do not manage servers or IP setup.
- Smart Lot Multipliers: Quantities are set per account in advance, so sizing does not depend on mental math during a fast move.
- Single Signal, Multi-Account Fills: One signal reaches the accounts you choose to link. Decide carefully which accounts belong in an intraday signal group, and confirm your configuration before going live.
Linking an account is not a reason to trade it actively. Use the tools to stay organized, not to increase activity in a retirement account.
Frequently Asked Questions (FAQs)
1. Can I trade in my parents’ demat account?
Only if you are authorized to do so under the broker’s rules, with your parents’ clear consent. Many people use a documented authorization or have the account holder place orders themselves. Confirm the correct route with the broker.
2. Should retirement money be used for intraday or options trading?
Most investors keep retirement savings away from high risk, short term trading. The right allocation depends on your parents’ needs, so it is worth discussing with them and, if needed, a SEBI-registered advisor.
3. How do I avoid mixing up accounts?
Keep separate plans, keep intraday signals limited to your own account, and double check which accounts are linked before each session.
4. Do I need coding skills or my own server?
No. Cirrus is a cloud-based web terminal. Static IP routing, token handling, and broker connections run on secure cloud servers.
5. How often should I review their portfolio?
Many families review quarterly, or when a major life event or market change happens. The right frequency is the one you and your parents agree on.
At a Glance: Key Takeaways
| Metric / Dimension | Mixed, Informal Approach | Separated, Documented Approach |
|---|---|---|
| Strategy | One style applied everywhere | Separate plans per account |
| Risk Level | Set by your appetite | Set by your parents’ needs |
| Authorization | Often informal | Clear and documented |
| Decision Record | Memory or chat messages | Written notes |
| Account Selection | Easy to mix up | Deliberate account linking |
| IP Compliance | Dynamic IP, higher rejection risk | Whitelisted static IPv4 routing |
What It Means for Your Family Finances
Looking after your parents’ savings is a position of trust. Doing it well matters more than doing it fast. A calm, documented process protects their money and protects your relationship with them.
The Bottom Line: Treat retirement money and intraday trading as two separate jobs. Get authorization, write the plan, keep strategies apart, and review regularly.
Want a cleaner setup for managing several accounts? Explore how Cirrus supports multi-broker execution across major Indian brokers with built-in static IP routing.
Key Facts at a Glance for Quick Reference
| Question | Answer |
|---|---|
| What is the core rule? | Keep retirement money and intraday trading separate |
| What comes first? | Clear authorization and a written plan |
| Who sets the risk level? | Your parents, based on their needs |
| How often to review? | On a schedule you agree on |
| Does a tool change the risk? | No, it only helps you stay organized |
| Who is it for? | Anyone managing family accounts alongside personal trades |
Disclaimer: Investments in securities markets are subject to market risks. Read all related documents carefully before investing. This article is for general information only and is not personalized financial, tax, or legal advice. KuberHunt and Cirrus do not provide investment advice through this content. Rules on operating another person’s account vary by broker, so please verify authorization requirements before managing accounts on behalf of family members. Consider consulting a SEBI-registered advisor for retirement planning